Skip to content

The 360 Series

Pension assets and life insurance: how can you protect your loved ones?

Not all assets are treated in the same way when someone dies. In Switzerland, pension assets and life insurance policies follow specific rules that can play a decisive role in protecting a spouse, child or unmarried partner. When properly coordinated with the rest of an estate plan, these solutions can become some of the most effective tools available to protect loved ones and preserve family wealth.

 

Découvrez l'importance de la prévoyance dans votre stratégie successorale.
Episode 6/9
Épisode 6 sur 9

Why do pension assets play such an important role in estate planning?

When people think about inheritance, they often focus on real estate, investment portfolios, savings accounts, or family businesses.

Yet a significant share of household wealth may be held in:

  • occupational pension plans;

  • Pillar 3a assets;

  • life insurance policies;

  • other retirement and protection solutions.

These assets are unique because they do not always follow the same rules as the rest of the estate.

As a result, they can be powerful tools for:

  • replacing lost income;

  • helping preserve the family home;

  • repaying debt;

  • maintaining a surviving spouse’s standard of living.

In some families, pension and insurance benefits are the first source of liquidity available after death.


Do all assets follow the same rules when someone dies?

Many people assume that all their wealth will automatically form part of the estate and be distributed according to inheritance law.

In practice, the situation is more nuanced.

Certain pension assets operate under dedicated beneficiary rules.

In some cases, benefits are paid directly to specific beneficiaries without passing through the ordinary estate distribution process.

This distinction is essential.

Two families with similar wealth may ultimately receive very different outcomes depending on how pension assets and insurance arrangements have been structured.

For this reason, an estate plan should not be limited to a will alone. Beneficiary designations, pension arrangements and insurance contracts should also be reviewed to ensure they reflect your wishes.

Pension savings

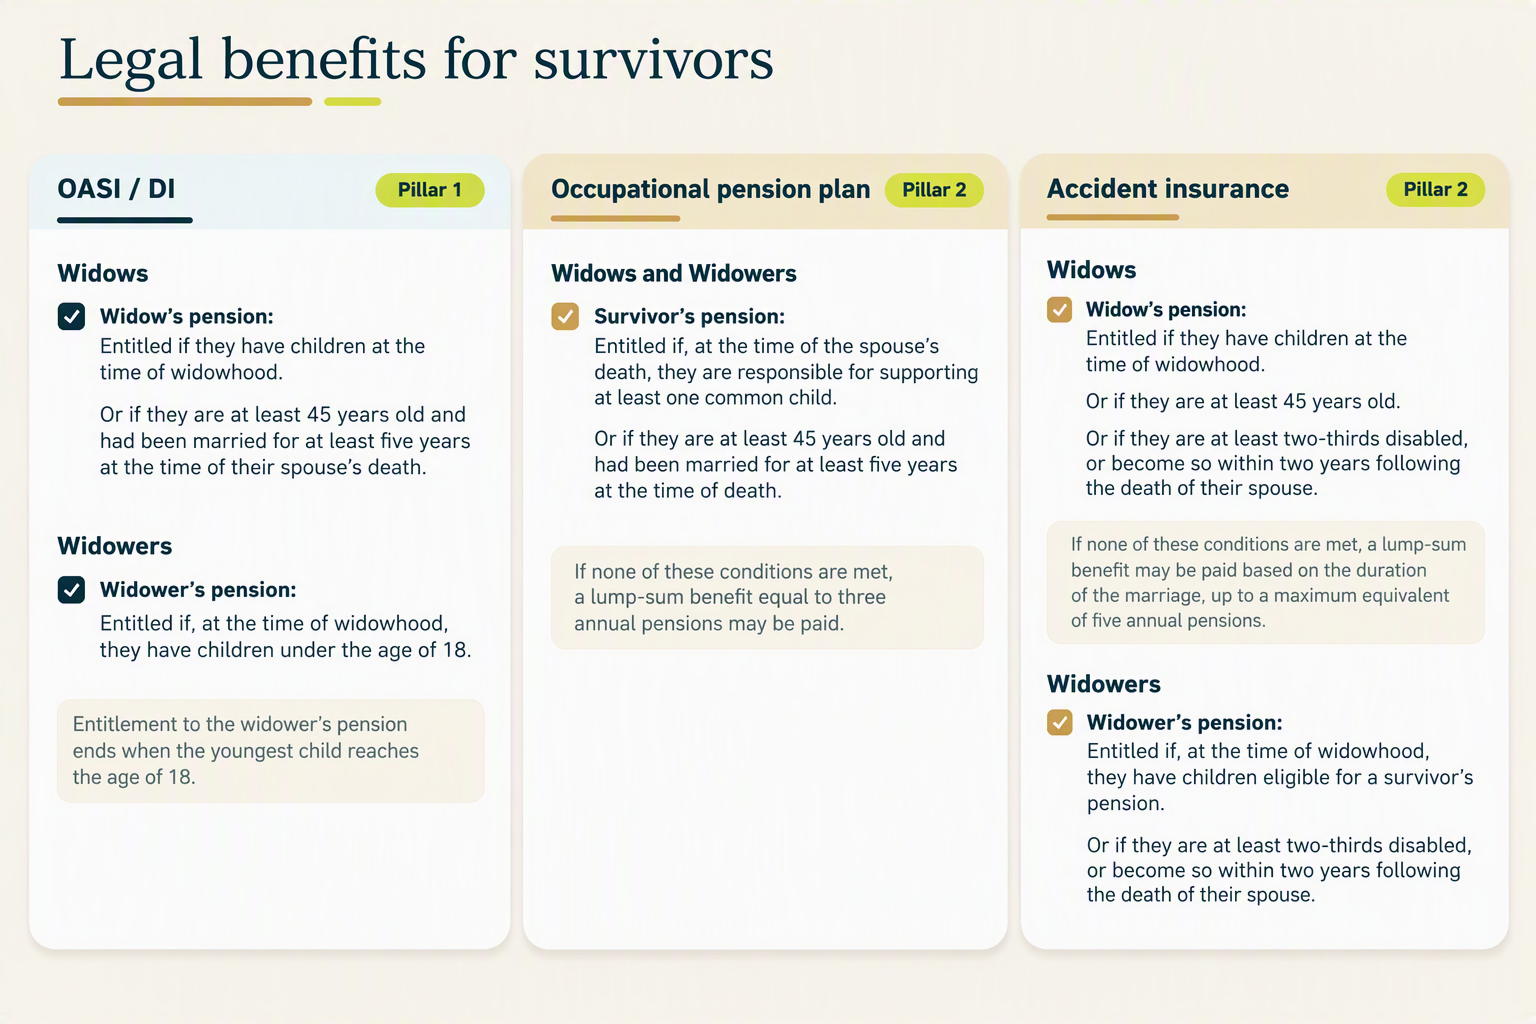
Statutory benefits under the 1st and 2nd pillars for survivors

Legal benefits for survivors

What happens to Pillar 3a assets on death?

Pillar 3a is often viewed solely as a retirement savings vehicle.

Yet it is also an important wealth transfer tool.

Unlike a traditional bank account, Pillar 3a assets are governed by specific beneficiary rules.

Who receives Pillar 3a assets?

Swiss law establishes an order of priority: a surviving spouse or registered partner is generally first in line.

If there is no spouse or registered partner, other beneficiaries may be considered, including:

  • descendants;

  • certain financially dependent individuals;

  • the life partner with whom the deceased lived as a couple for the five years prior to their death, or who is responsible for providing for their joint children;

  • parents;

  • siblings;

  • other statutory heirs.

This hierarchy is specific to Pillar 3a and should not be confused with the ordinary rules of inheritance.


Can you choose your beneficiaries freely?

Yes, but only within certain limits.

Contrary to a common misconception, Pillar 3a assets cannot always be left freely to any beneficiary of your choice.

The law establishes an order of beneficiaries. However, some flexibility remains available.

Depending on your family circumstances, it may be possible to:

  • favour certain beneficiaries;
  • adjust the allocation between beneficiaries;
  • provide for a life partner under specific conditions.

Why is Pillar 3a particularly important for unmarried couples?

Cohabiting partners are among the groups most exposed under inheritance law.

An unmarried partner is not a statutory heir. However, Pillar 3a can significantly improve their financial protection in certain situations.

For many unmarried couples, beneficiary planning within Pillar 3a is one of the most important estate planning considerations.

What happens to your occupational pension on death?

Occupational pension assets often represent a significant share of a family's overall wealth.

However, the benefits paid out in the event of death are not the same across all pension funds.

They depend on the rules of the relevant pension fund.

Benefits for surviving family members

Depending on the pension fund and the family situation, benefits may include:

  • a survivor’s pension for a spouse;

  • a pension for a recognised partner;

  • an orphan’s pension;

  • a lump-sum death benefit;

  • other forms of survivor protection.

These benefits can play an essential role in maintaining financial stability after a death.

Why should beneficiary arrangements be reviewed regularly?

Many people assume their loved ones are adequately protected without ever checking the administrative details.

In practice:

  • a partner may never have been registered;
  • certain eligibility requirements may not be met;
  • beneficiary arrangements may never have been updated following changes in family circumstances.

Regular reviews help ensure benefits are paid to the people you actually intend to protect.

How does life insurance fit into an estate planning strategy?

Life insurance often serves as a bridge between pension planning, estate planning and family protection.

Its primary advantage is liquidity. It can provide capital immediately after death, even when much of the family's wealth is tied up in property, investments or a business.


Term life insurance

Term life insurance pays a capital benefit if the insured person dies during the insured period.

It can be used to:

  • repay a mortgage;

  • preserve the family home;

  • compensate for lost income;

  • maintain the family’s financial stability.​‌

Life insurance within Pillar 3a

Some Pillar 3a solutions take the form of life insurance contracts.

These arrangements typically combine:

  • retirement savings;

  • death benefit protection;

  • disability cover in certain cases.

As with other Pillar 3a assets, beneficiary rules follow the framework established for tied pension assets.

Life insurance within Pillar 3b

Life insurance held within Pillar 3b generally offers greater flexibility. Beneficiaries may be designated more broadly in accordance with the terms set out in the contract.

Depending on the structure of the policy, it may be used to:

  • provide for an unmarried partner;

  • create liquidity for the family;

  • complement a broader estate planning strategy.

This is one reason why life insurance is often reviewed alongside wills, pension planning and matrimonial property arrangements.

Which questions should you review regularly?

Beneficiary clauses and contingency arrangements should not be regarded as set in stone.

It is useful to ask yourself the following questions regularly:

  • Are my beneficiaries still up to date?

  • Would my spouse or partner have sufficient financial protection?

  • Could the family home be retained?

  • Would the planned benefits be sufficient?

  • Does my will remain consistent with my pension and insurance arrangements? 

  • Will my children be treated in accordance with my wishes?
Key takeaways

  • Pension assets and life insurance do not always follow the same rules as the rest of an estate.

  • Pillar 3a, occupational pensions and life insurance are among the most effective tools available to protect loved ones.

  • For unmarried couples, coordinating estate planning, pension planning and insurance arrangements is often essential.

Let's talk about your legacy

Pension assets and insurance arrangements often play a much greater role in wealth transfer than many people realise.

Our specialists can help ensure that your estate plan, pension arrangements and insurance solutions work together to protect the people who matter most to you.

In the next episode

Discover some of the most complex inheritance situations: blended families, unmarried couples, family businesses and substantial real estate holdings.

You will learn how to balance family protection, fairness between heirs and the preservation of family wealth.​‌

FAQ

Frequently asked questions about pension assets, life insurance and inheritance​‌

The 360 Series

The "Estate Planning in Switzerland" series

Turning life’s ambitions into lasting legacies.

This 360 series provides the essential insights you need to understand estate planning in Switzerland, helping you protect your loved ones and transfer your wealth with confidence.

  • Episode #1

    Estate planning in Switzerland: protecting and transferring your wealth

    Why plan your estate and protect the people who matter most?

  • Episode #2

    Swiss inheritance law

    Who will inherit your assets if there is no will?

  • Episode #3

    Matrimonial property regime and inheritance

    What belongs to your spouse before the estate is divided? 

  • Episode #4

    Wills and inheritance agreements

    How can you organise your estate according to your wishes?

  • Episode #5

    Lifetime gifts and advancements on inheritance

    How can you transfer wealth during your lifetime while preserving fairness among your heirs?

  • Episode #6

    Pension assets and life insurance

    How can you protect your loved ones through pension planning, Pillar 3a and life insurance?

  • Episode #7

    Complex succession situations

    How can you protect your family, your cohabiting partner or your business?

  • Episode #8

    Inheritance and gift tax

    Which taxes apply, and why do they vary from canton to canton?

  • Episode #9

    Planning your estate in five steps

    A five-step method to help you plan the transfer of your estate with peace of mind.

The information presented in this series is provided for general information purposes only and does not constitute personalised legal, tax or wealth planning advice. Family, financial and tax circumstances vary, and the implications of an inheritance or wealth transfer may differ significantly from one situation to another. Before making any decision, you should seek advice from a qualified specialist who can assess your individual circumstances.

A unique blend

A life project is not something you share with just anyone.

Dedicated experts in every field.

  • Private banking

    Investment

    From investment advice to delegated portfolio management, we are dedicated to safeguarding your capital and securing its growth by identifying investment solutions that align seamlessly with your values, goals, and the assurance of peace of mind.

  • Private banking

    Wealth & Pension
    advice

    Bring vitality and success to your life projects by comprehensively analyzing your assets and optimizing their structure.

  • Private banking

    Financing

    We offer various financing solutions for all your real estate projects, such as mortgages and Lombard loans.
Piguet Galland & you

Piguet Galland DNA

More than a friend,
a Piguet Galland private banker.

To provide you with the best possible support, we want to understand what keeps you awake at night, your plans, and your dreams. Our expertise lies in aligning your assets with projects close to your heart.​‌

Your trusted partner

We understand that you expect more from us than trust and expertise. Above all, you want peace of mind for both the future and the present. It's our responsibility to deliver.​‌

French-speaking and close to you

Because we are close to you, where you need us, and available when you need us, we conduct our wealth management business with agility and efficiency and always with a smile.
A human-scale bank backed by a solid financial group

Our majority shareholder, Banque Cantonale Vaudoise, is one of the few major banks in the world without a state guarantee, and it holds an AA rating from Standard & Poor's. This is concrete proof of our results.


Meet a specialist

Your time is precious, and we're committed to making this process as smooth as possible.