Digital transformation in private banking: Milena Maksimovic's perspective
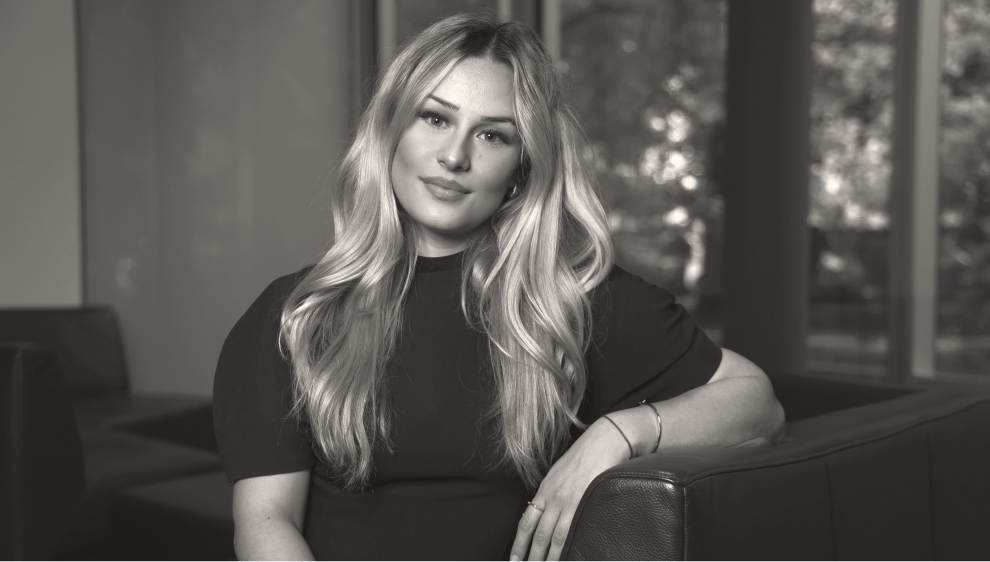
-
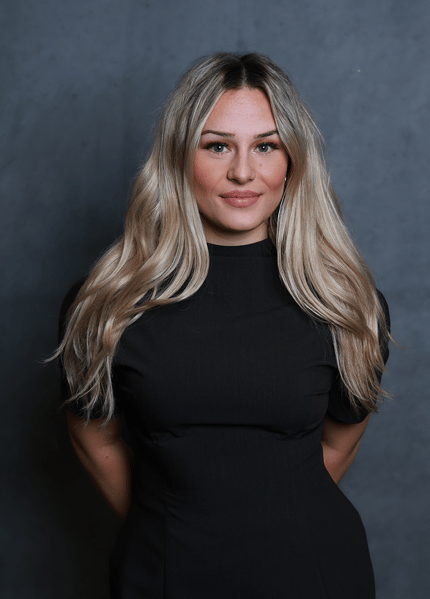
Milena Maksimovic Independent Asset Management Intern
An internship at the intersection of client experience, wealth management and digital transformation.
Milena Maksimovic joined Piguet Galland as part of her Master's degree in Wealth Management (GEMWeM) and is completing her internship within the Independent Asset Management (IAM) department. This experience brings together wealth management, digital transformation and client experience in private banking.
Early in her internship, Milena became involved in a major project: the migration to Piguet Galland's new e-banking platform. Working directly with clients, she helped them navigate and become familiar with the new environment. This experience gave her first-hand insight into the challenges of digital transformation: understanding changing user behaviours, supporting clients through change and listening to their needs.
From private clients to Independent Asset Managers
Following this initial experience, Milena is now contributing to another strategic project: the implementation of a new platform designed for Independent Asset Managers (IAMs).
This new learning opportunity allows her to gain a deeper understanding of the specific needs of wealth management professionals and contribute to the development of the tools available to them.
When professional experience informs academic research
This professional experience is also closely connected to Milena's academic journey.
As part of her Master's degree, her research focuses on digital adoption and client engagement in Swiss private banking, examining changes in client behaviour following the introduction of Piguet Galland's new e-banking platform.
The subject directly reflects the projects she has been involved in, allowing her to compare academic findings with practical experience.
In this interview, Milena shares insights into her journey, her experience working with clients and Independent Asset Managers, and the digital developments that are gradually reshaping private banking.
In conversation with Milena
Could you briefly introduce yourself and explain what attracted you to Piguet Galland?
My name is Milena Maksimovic. I hold a Master’s degree in Wealth Management from the University of Geneva, and I am currently completing an internship at Piguet Galland within the Independent Asset Management team.
What first drew me to the bank was its distinctive position within the Swiss banking landscape. Since the end of banking secrecy, the sector has undergone significant consolidation, leading to a clear polarisation between a handful of banking giants and a small number of mid-sized institutions that have successfully reinvented themselves.
Piguet Galland is one of them. Its resilience, I believe, stems from its positioning: strong local roots and close ties with entrepreneurial clients. This proximity changes the nature of the relationship. We meet clients regularly, and we build relationships that go well beyond financial performance alone.
The bank’s human scale, with approximately 180 employees, was another decisive factor. I noticed it from the very beginning of my internship: I have become familiar with every department, and I can speak directly with colleagues, ask questions and suggest improvements to processes.
There is an almost entrepreneurial spirit within the organisation: if a project makes sense, it can genuinely become reality. This is rare in today’s banking sector, where institutions tend to compartmentalise their data and practices. That is what ultimately tipped the balance for me.
You played an important role in supporting clients during the migration to our new e-banking platform. What did you take away from this experience?
An e-banking platform is a source of real added value in itself: it allows clients to monitor and manage their finances independently. It is often the first technological touchpoint clients have with their bank, and it is all the more powerful when its UX/UI is intuitive, as is the case at Piguet Galland.
This experience nonetheless confirmed that, in digital transformation, technology alone is not enough. Human support is essential to adoption, both for clients less familiar with digital tools and for those who run into technical difficulties. McKinsey’s 2023 research on the banking customer experience makes the same point: emotionally charged interactions, particularly problem resolution and moments of friction, weigh disproportionately on the overall experience and on clients’ trust in their bank. This is exactly what I observed in the field. Far from being reluctant, clients welcomed this support with enthusiasm, some even travelling to the bank to benefit from it. A few compared the appointment to a visit to their doctor or tax adviser, and some still call me by my first name today.
Finally, this experience taught me an organisational lesson: this level of proximity is only sustainable if the support structure is designed in advance. Clearly defined escalation levels for technical issues ensure that the human touch is not lost in the procedure.
Has working directly with clients during a digital transformation changed your perception of their expectations regarding banking technology?
Absolutely. What struck me most was the diversity of expectations across different client profiles. An active entrepreneur may prefer to place orders independently, whereas a more passive wealth management client may expect greater support and guidance. We are far from dealing with a homogeneous client base. Private banking must now respond to expectations of speed and digital autonomy inherited from retail banking and fintech companies, while maintaining a regulatory framework and level of personal service that differ considerably from those standards. This tension between the democratisation of tools and the demand for personalisation is, to my mind, the most intellectually stimulating aspect of the profession, and it raises a real question of how to segment the digital offering by client profile.
In practical terms, this experience taught me that a relationship manager must constantly balance three dimensions: client expectations, the risks associated with each functionality and what the bank can realistically provide. For every request, the question is not simply “Is this technically feasible, and at what cost?” It is also “Which client is this intended for?” It means considering their risk profile, the suitability of the service and Know Your Customer (KYC) compliance requirements.
This trade-off between innovation and prudence is, in my view, at the heart of banking today.
You are now working on the new platform for Independent Asset Managers. How does this project differ from your previous work, and what are you learning from it?
Independent Asset Managers represent a strategic growth area for Swiss private banks today. According to a study published in 2026 by the WealthSummit platform, there are more than 1,300 Independent Asset Managers authorised by FINMA, together managing close to CHF 850 billion in assets. This means the project addresses a strategic challenge, rather than simply a technical one.
The fundamental difference lies in the end-user model. We are moving from a business-to-consumer (B2C) approach, as with traditional e-banking, to a business-to-business-to-consumer (B2B2C) model. The user is no longer the end client but a professional acting on behalf of their own clients and managing dozens of portfolios simultaneously. We are no longer designing a tool for an individual’s convenience, but a complete, fully functional working tool: speed of execution, a consolidated multi-client view and aggregated reporting. Piguet Galland becomes a technical and custody provider for a third party. The proximity I mentioned earlier does not disappear; it shifts. Independent Asset Managers also need prompt, efficient support, not least because they often juggle several custodian bank platforms. This responsiveness encourages adoption of the tool and, over time, reduces the operational workload of our internal teams.
Finally, the project has confronted me with a more technical reality: the need to work with external providers when the infrastructure requires it, which adds a further layer of coordination and complexity, an aspect of the profession I am discovering. Support must take into account users’ requests, queries, complaints and feedback, then assess the feasibility and cost of any new feature with the provider.
Your Master’s research focuses on “Digital Adoption and Client Engagement in Swiss Private Banking”. Why did you choose this subject, and what aspects are you particularly interested in exploring?
This subject emerged directly from the field. As the point of contact for support, I saw first-hand how important human support was. While supporting clients through the migration, I began to wonder whether the new features alone would be enough to drive adoption of the tool, and above all whether that adoption would be uniform, given the diversity of profiles and mandates that coexist in private banking.
Since the 2000s, academic literature has generally presented digitalisation as a driver of mass adoption. However, most of this research focuses on retail banks, where client bases tend to be more standardised.
My thesis therefore tests the classic technology adoption frameworks, namely the Technology Acceptance Model (TAM), its extension TAM2 and the Self-Service Technology (SST) model, against Piguet Galland’s e-banking data, before and after the introduction of the new platform.
This analysis helped me understand that perceived usefulness remains the most significant factor, but that its weight varies considerably depending on how much of their finances the client delegates. Other secondary determinants, such as ease of use and the quality of support, also play a significant role. These preliminary findings suggest that digital adoption in private banking is structurally more complex than in retail banking: it demands a much higher degree of personalisation.
How does your practical involvement in these projects inform your academic research, and vice versa?
I believe academic work can prove valuable in situations where a decision carries significant consequences, such as a technology investment in private banking. It makes it possible to sketch, up front, an initial reading of a bank’s client base: their risk appetite, age, digital literacy and the degree to which they delegate their finances, depending on the mandate. These are indicators that help anticipate, without guaranteeing, how likely the tool is to be adopted and how much support it will require.
A common assumption holds that clients are more digital today and expect their bank to be too, and a KPMG study on wealth management points in that direction, noting a growing demand for digital experiences. A more recent Swiss study qualifies this finding, however. Conducted in autumn 2025 by e.foresight and the Geneva School of Business Administration (HEG Genève) among Swiss and Liechtenstein private banks, it shows that a large share of clients still prefers human contact, and that around half of institutions still operate on a “physical-first” model. The sector’s lag is therefore no accident: banks must not miss the technological train, but they must also estimate precisely how much to invest and where to focus it. A thorough understanding of the market and client base is essential before committing resources: prudence should take precedence over trends.
Conversely, the field confirms or qualifies this theoretical reading. Piguet Galland’s post-migration data broadly corroborated the trends identified beforehand, while revealing nuances about clients that theory alone could not have captured. My takeaway is that theory provides an initial orientation before investing, and that the field allows it to be adjusted.
Beyond the projects themselves, what has your experience at Piguet Galland taught you so far, both professionally and personally?
Professionally, what has struck me most is the demanding nature of working directly with Independent Asset Managers. It requires a broad combination of skills: interpersonal abilities to support clients and build relationships, alongside more quantitative and technical expertise. It is not a profession that focuses exclusively on either relationships or analysis, and it is this dual requirement that makes it so rewarding.
On a personal level, what I take away above all is the strength of the collective. Everyone on the team is highly competent in their own field, with their own specialties, and it is this complementarity that creates a genuine bond of trust. That trust has been demonstrated in very practical ways. I was given responsibility relatively quickly, particularly in areas involving data processing and automation. To me, this reflects the human scale of the bank that I mentioned earlier: everyone is recognised for what they contribute, regardless of their position or status.
Ultimately, what I take away from this experience is that combining technical and interpersonal skills can be a powerful driver of collective performance when the two are effectively brought together.
Looking ahead, which areas or skills would you like to develop further?
So far, I have worked extensively on the technical and data-related aspects of the business, which has given me a solid understanding of internal workflows. What I would now like to explore further is the commercial side: having more direct contact with clients and Independent Asset Managers, understanding the business rationale behind decisions, and discovering how the analytical skills I have developed can contribute to a more strategic approach to the profession.