Europe: politics, a new source of volatility?
In Germany, although federal elections are not scheduled until 2029, regional elections are increasing pressure on the government. Following the AFD’s victory in Saxony-Anhalt, this weekend’s elections confirmed the weakening of the CDU, which suffered a historic setback in Mecklenburg-Western Pomerania and lost Berlin to Die Linke.
These results have intensified questions surrounding Friedrich Merz’s leadership, with his approval rating falling to 10%, and increased the pressure on the government to deliver stronger economic growth. Nevertheless, the fiscal stimulus measures and planned investments are unlikely to be called into question. Financial markets remained largely unmoved by the results, with the German equity market even gaining ground on the day following the votes.
In France, the political situation appears more challenging, with public finances under strain and debt continuing to rise. However, these vulnerabilities are already well recognised by financial markets, with the OAT-Bund spread currently standing at an all-time high. It is expected to remain a key barometer of French political risk in the run-up to the 2027 presidential election.
US equity valuations in free fall
The S&P 500 Index is likely to close September in negative territory. Investors have had no shortage of reasons to move away from US equities in recent weeks. Ten-year government bond yields approaching the 5% threshold and the Federal Reserve’s first interest-rate increase since 2023 are the principal factors behind the pause observed in equity markets in September.
This is indeed a pause rather than a genuine correction. The leading US equity index is trading barely 3% below the record highs reached in August and is once again demonstrating remarkable resilience. Neither the rebound in oil prices above USD 100 per barrel nor the approach of the highly uncertain midterm elections appears sufficient to trigger a material downturn in the equity market.
Yet valuations continue to decline significantly. The S&P 500’s price-to-earnings ratio (P/E) has returned to the level seen in March, when the US-initiated conflict in Iran began, namely 19x. This also represents a correction of nearly 20% from the 23x level observed in 2025.
What is currently supporting equity markets is the exceptional growth in US corporate earnings. Indeed, 2026 is set to be a record year for earnings growth. Profits at US companies are expected to increase by 30% this year, a figure that was revised sharply upwards following 45% growth in the second quarter.
The third-quarter earnings season is fast approaching. However, even though profits remain on a positive trajectory, with analysts forecasting growth of 27%, the trend is moving towards normalisation following the exceptionally high levels recorded in the previous quarter.
Given the numerous uncertainties characterising the current environment, continued earnings growth will be essential to support equity markets. Without this growth, driven by massive investment in artificial intelligence-related technologies, stock-market performance would undoubtedly be considerably less favourable.
Some of these uncertainties could potentially dissipate over the coming weeks. A resolution of the conflict in the Middle East, a decline in long-term interest rates and a clear, uncontested outcome in the midterm elections could all help bring the sharp contraction in valuation multiples to an end.
This would create a considerably more favourable backdrop heading into the final two months of the year, a period that has historically been supportive of equity markets. Earnings growth may have reached its peak and cannot sustain the US equity market indefinitely
This week’s figure 5%
The rise in US 10-year Treasury yields was halted at the psychologically significant 5% threshold. This represents a major technical resistance level, corresponding to the peak in yields reached in October 2023.
Author
-
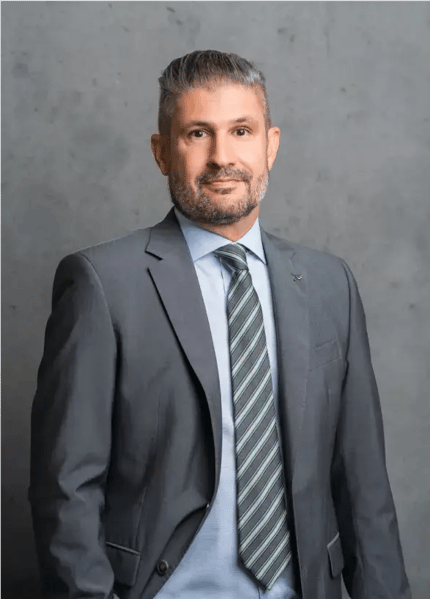
Daniel Steck brings nearly twenty‑five years of experience in the financial sector. He began his career in financial analysis at Lombard Odier, focusing in particular on the healthcare sector, before continuing at Reyl & Cie as an analyst and portfolio manager. He joined Piguet Galland in 2018 as a Senior Portfolio Manager, where he is responsible for managing equity funds and thematic certificates invested in Switzerland and North America.